 ع


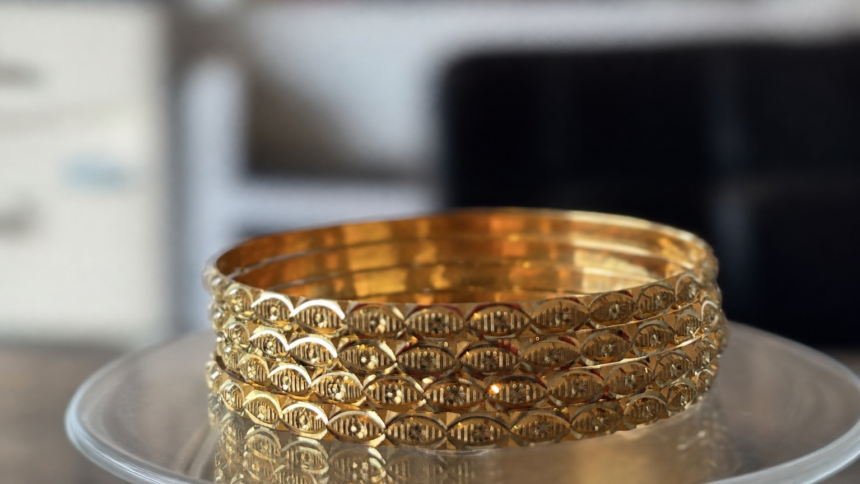
A mid-October report in The Economic Times outlined how owners of idle gold jewellery can obtain cash within hours by pledging it as security for a loan while retaining ownership of the asset. The process requires minimal documentation compared with personal loans, often involving only verification of the gold’s purity and weight before disbursement on the same day. This method has grown in popularity as gold prices climbed, allowing individuals to unlock value without parting with family heirlooms or cultural assets that hold both monetary and sentimental worth.
India holds an estimated 25,000 tonnes of privately owned gold, the bulk of it stored unused in lockers, according to assessments cited in the report and a Jefferies note from August.[[1]](https://www.newindianexpress.com/business/2026/Aug/31/rising-gold-prices-could-add-up-to-100-bps-to-gdp-jefferies) A separate analysis placed the value of these household holdings at roughly 3.9 trillion dollars by March 2026, reflecting both accumulated stocks and the recent price appreciation. World Gold Council data has consistently shown gold’s central place in Indian household wealth, where its share rose from 15.4 percent in March 2023 to 24.2 percent three years later.[[2]](https://www.livemint.com/money/personal-finance/indian-household-asset-allocation-shifts-gold-share-jumps-from-15-to-24-in-3-years-equity-barely-moves-11789042937726.html)
Gold loans typically carry interest rates between 8 and 12 percent, markedly lower than the 12 to 24 percent common for unsecured personal borrowing, the Economic Times report stated. The Reserve Bank of India maintains a 75 percent loan-to-value cap, meaning borrowers can access up to 75 rupees for every 100 rupees of gold value. Repayment structures offer flexibility, ranging from monthly interest-only payments with principal due at maturity to standard EMIs, suiting varied short-term cash requirements.
The broader gold loan market expanded 62 percent year-on-year to 21.7 lakh crore rupees in the quarter ended June 2026, JM Financial data shows.[[3]](https://www.newkerala.com/news/a/gold-loan-portfolio-jumps-62-rs-217-lakh-976.htm) Reserve Bank of India figures released in early October placed bank loans against gold at 5.6 lakh crore rupees in August, an 83 percent annual increase, while non-banking financial company portfolios reached 3.6 lakh crore rupees after 69 percent growth. Lenders including Central Bank of India have set ambitious targets, aiming to lift their books from 41,000 crore rupees currently to 1.1 lakh crore rupees by September 2027 through dedicated verticals and improved underwriting.
Borrowing against gold enables investors to meet immediate needs without redeeming equities or mutual funds at depressed prices during market downturns, according to the Economic Times analysis. The approach preserves the underlying asset for potential future appreciation while providing liquidity that can be repaid once conditions improve. Recent lender disclosures have nevertheless flagged early stress signals, including rising 30-day delinquencies at some non-banking institutions amid rapid sector expansion and volatile gold prices.
Industry estimates from CRIF High Mark placed the overall gold loan portfolio at 21.7 lakh crore rupees as of June, with the Reserve Bank noting compounded annual growth of 42.4 percent since March 2024 that warrants ongoing monitoring.[[4]](https://www.ndtvprofit.com/economy/is-there-a-ticking-time-bomb-in-indias-gold-loan-portfolio-12214515) Delinquency rates remain contained below 2 percent at several major players, yet analysts caution that rollovers tied to higher gold values could mask underlying borrower pressure. The trend nevertheless underscores gold’s evolving role from purely dormant holdings to an active collateral instrument across both rural and urban India.