 ع


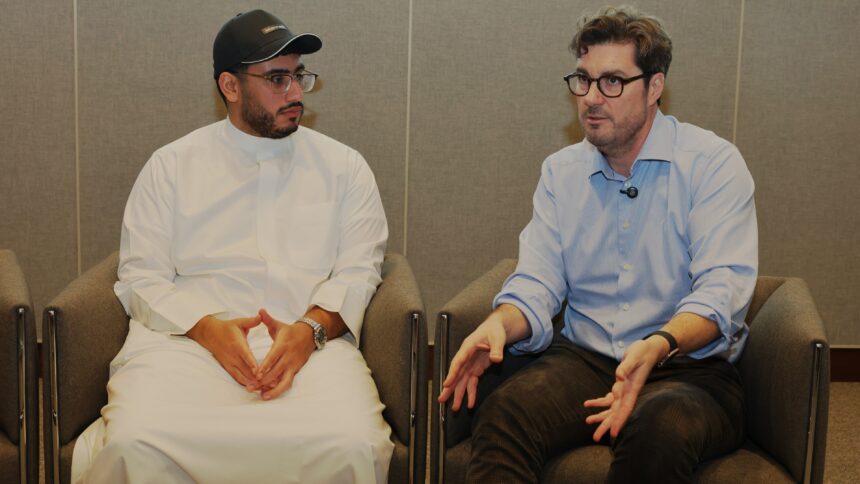
Oxford Risk’s Head of Behavioural Finance explains how AI could make individual financial support more accessible, and why better outcomes depend on the systems behind it.
Artificial intelligence could widen access to personalised financial support by reducing the cost of adapting guidance to each individual, according to Dr Greg B Davies, Head of Behavioural Finance at Oxford Risk.
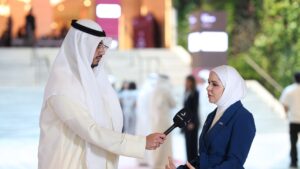
Speaking to Diwaniya Media at Lei Wa Lakom’s Women & the Economy conference in Kuwait, Davies argued that AI could help overcome a practical constraint that has limited the application of behavioural science in finance. Understanding how people make decisions has advanced considerably; delivering support tailored to those differences has remained difficult and expensive.
“AI is starting to make, I think, the promise of behavioral finance come alive,” he said, explaining that personalisation at scale was becoming “cheaper, faster, and easier.”
Davies’s perspective draws on a career spanning academic research and financial services. According to his Oxford Risk biography, he holds a PhD in Behavioural Decision Theory from Cambridge, established a behavioural finance team at Barclays in 2006 and led it for a decade. He joined Oxford Risk in 2017 to develop behavioural software supporting financial decisions.
The economics of individual support
Davies described a longstanding gap between behavioural finance’s insights and their practical application. The field, he said, has developed a substantial understanding of decision-making without having an equivalent influence on everyday financial outcomes.
“You need to personalize what you deliver to them,” he said of helping people make better decisions.
That requirement gives the adoption of AI a particular significance. A service built around individual needs must understand the person receiving it and adapt its communication accordingly. Davies sees AI as a way to make that process more feasible across a large customer base.
His argument concerns the delivery of financial support, including the explanation of decisions and the help people receive in acting on them. Reducing the cost and complexity of personalisation could allow behavioural insights to reach more of the people they are intended to assist.
The distinction matters when assessing the technology’s value. Faster responses and more natural conversations may improve the experience of using a service. Davies’s ambition goes further: support that helps an individual navigate a decision and feel sufficiently confident to carry it through.
Why access and confidence matter
Research from the UK illustrates some of the barriers financial services must address.
The Financial Conduct Authority reported that just 9% of adults received advice about pensions or investments in the 12 months covered by its Financial Lives 2024 survey. Among adults who had not received advice and held at least £10,000 in cash savings, 24% said they did not invest because they lacked sufficient knowledge, while 12% felt overwhelmed by the choices available.
These figures describe UK consumers. They nevertheless illustrate the kind of obstacles relevant to Davies’s argument: uncertainty about financial choices and difficulty identifying an appropriate course of action.
Different obstacles also call for different forms of assistance. Someone seeking an explanation of investment terminology has different needs from someone requiring a recommendation based on their full financial circumstances. A useful personalised service must recognise the scope of the question as well as the circumstances of the person asking it.
For financial institutions considering AI, that makes the quality of the initial conversation consequential. The system needs to establish what help is required before adapting how it delivers that help.
Helping people carry decisions through
Davies places particular weight on what happens after a person receives a recommendation. Financial decisions unfold in changing circumstances, with market fluctuations testing the confidence behind an earlier choice.
He argued that financial services often leave individuals carrying much of the burden of acting and remaining emotionally comfortable with their decisions. Behavioural science, in his view, offers a way to build more of that support into the service itself.
“It’s about helping them with the actual process of decision making and the actual process of enacting those decisions so that they actually get to better outcomes,” he said.
Personalisation, understood in those terms, extends beyond presenting information in a preferred format. It involves attention to how an individual understands a choice, what makes that choice difficult and what assistance is needed to implement it.
This gives his argument a longer time horizon than a single interaction with a chatbot. Financial resilience and wellbeing depend on decisions made and maintained over time. Assessing a service against those goals would require looking beyond whether its users found an answer helpful in the moment.
The systems behind the conversation
A 2025 study by researchers at the University of Tokyo and the University of Glasgow examined personalised financial conversations using large language models. Its laboratory study involved 64 participants working through simulated investment scenarios.
The researchers found that AI advisers could elicit investor preferences, but that resolving conflicting needs remained difficult. The accuracy of that initial understanding mattered: when preferences were captured incorrectly, personalised guidance could have little effect or direct participants towards unsuitable assets.
The experiment did not establish improvements in long-term investment returns or household financial wellbeing. It did, however, illustrate why a convincing conversation needs to be grounded in a reliable understanding of the person’s needs.
Davies’s proposed approach addresses the underlying design. He advocates using AI above understood, rules-based systems whose inputs and outputs can be examined. Within that structure, AI could accelerate the process and personalise how an answer is delivered.
“AI should not be making up the answer,” he said.
The opportunity he describes therefore carries a clear condition. Making individual support cheaper and easier to deliver is valuable only if the resulting service helps people understand their options and make suitable decisions. For providers, the measure of progress would be evidence that those benefits endure beyond the conversation.