 ع


The Saudi platform’s $1.7 million funding round backs an expansion focused on the agreements, stock and payments behind entry into physical shops.
Saudi retail technology company Raff is expanding its work connecting consumer brands with physical shops after securing $1.7 million in pre-seed funding. The business is addressing a specific stage in a brand’s development: moving from selling through its own online channels to managing stock, orders and commercial relationships with other retailers.
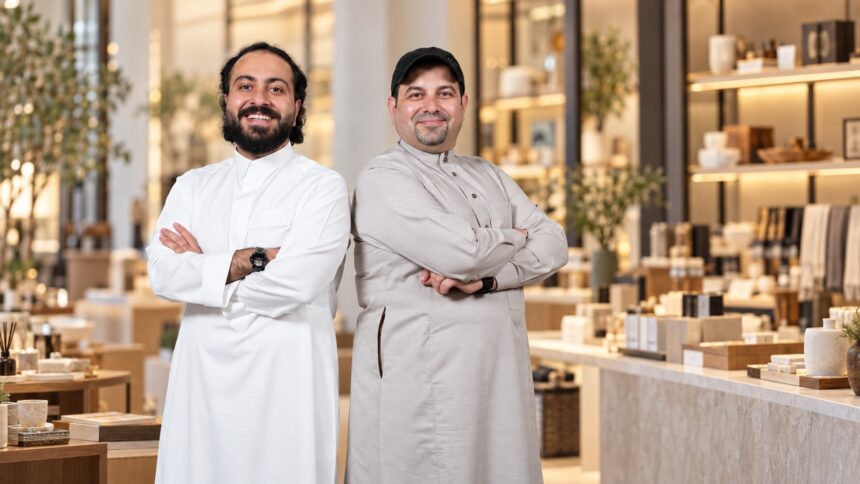
The round announced in August was led by Vision Ventures, with participation from 500 Global, Palm VC, Oqal and Salla co-founder Salman Butt, among others. Founded in 2024 by Ali Al Qudah and Abdul Kareem Munla, Raff plans to use the investment for GCC expansion, product development and artificial intelligence capabilities.
Its direction adds another dimension to the region’s retail technology story. Digital infrastructure is being used to organise transactions between brands and shops, as well as purchases made by consumers online. The distinction matters because distribution agreements, replenishment and settlement sit behind the products shoppers eventually encounter on a shelf.
Gulf brands crossing into new retail markets
Two examples described by chief executive Ali Al Qudah in an interview with Inc. Arabia show the type of transaction Raff is pursuing. Teebmade, a Saudi giftware brand drawing on local culture and craftsmanship, joined the platform in mid-2026. Within weeks, it was selling through seven physical retailers across Saudi Arabia and the UK, according to Al Qudah.
He also cited Nazek Gifts, a personalised gifting business from Kuwait. After starting to work with Raff in mid-2026, the brand was selling through six retailers in Saudi Arabia within weeks. These are company-reported examples of distribution reach, rather than disclosed sales figures or independent measurements of consumer demand.
The two routes illustrate different commercial movements: a Saudi business reaching domestic and overseas shops, and a Kuwaiti supplier entering the Saudi market. Al Qudah said Raff had retailer partnerships in Saudi Arabia, Kuwait, Bahrain and the UAE. That places the company’s operating network across several markets, rather than making its regional ambition solely a future funding objective.
Online growth alongside a wider trading economy
Saudi statistics provide a useful distinction between the growth of online sales and the performance of trade overall. In its second-quarter 2026 release, published on August 30, the General Authority for Statistics reported that the operating revenues index for wholesale and retail trade increased by 3.2% from a year earlier.
The e-commerce sales index rose by 9.8% over the same period. Within that index, retail trade recorded growth of 13.4%, compared with 6.5% for wholesale trade and 2.4% for the sale and repair of motor vehicles. The retail e-commerce component also increased by 1.1% from the first quarter.
These figures measure changes in indices, not the proportion of Saudi purchases made online. They show digital sales growing within a broader trading economy; they do not establish that physical stores are being replaced, or measure demand for any individual distribution platform.
For Raff, the relevant connection is between those channels. A brand can maintain online sales while placing products with retailers that serve customers in person. The resulting commercial relationship involves both businesses, even when the eventual customer purchase happens away from the brand’s website.
Physical retail remains a substantial regional market
A separate view comes from Alpen Capital’s GCC Retail Industry Report 2024. Its forecast put regional retail sales at $386.9 billion in 2028, up from $309.6 billion in 2023, equivalent to annual growth of 4.6%. These are projections made in 2024, rather than a measurement of the market today.
The report expected Saudi Arabia and the UAE together to account for 77.7% of GCC retail sales by 2028. It projected non-food sales growth of 4.3% a year across the region, compared with 5% for food. For a business serving consumer brands, that distinction separates the broad retail economy from the particular categories its suppliers sell.
Alpen also anticipated additional organised retail space. Under a scenario assuming 80% completion of projected additions, the GCC would gain 3.9 million square metres between 2023 and 2028. Its analysis considered online commerce and physical retail investment within the same regional outlook, alongside retailers’ adoption of business models connecting multiple sales channels.
The transaction behind the shelf
Raff’s current platform description puts agreements, purchase orders, inventory, fulfilment and payments within the same business relationship. Its website lists more than 900 brand partners, more than 30 retail partners and a network spanning nine countries. Those are company figures with different units: a brand count should not be read as a count of shops or completed purchases.
The operational emphasis is on the records shared between buyer and supplier. A catalogue identifies the goods available; an agreement establishes the commercial terms; an order records what the retailer requests. Inventory and sales reporting then concern what happens after stock enters the retail channel. Returns and restocking extend that relationship beyond an initial delivery.
That explains why Raff’s announced development programme combines regional expansion with software investment. Increasing the number of markets also increases the number of commercial relationships being administered. The next reported stage is the deployment of the new capital across that network, with distribution and its supporting records at the centre of the company’s expansion.