 ع


Knight Frank India figures show sales across the eight tracked cities reached 86,767 units during the July to September period, marking a 1 percent decline from the same quarter in 2025 while holding steady compared with the preceding quarter. Cumulative sales for the first nine months of the year stood at 258,238 units, matching the total recorded in the corresponding period of 2025. The consultancy noted that sales in the seven markets outside Delhi-NCR rose 2 percent year on year, offsetting weakness in the capital region.
The slowdown remained concentrated in Delhi-NCR, where Knight Frank India data places third-quarter sales at 10,712 units, a 17 percent drop from a year earlier and the lowest quarterly figure since the third quarter of 2021. The region has failed to record any year-on-year growth since the first quarter of 2024, with 86 percent of its sales occurring in the premium segment priced above INR 10 million. This performance contrasted with gains elsewhere, as the report highlighted how the broader market is consolidating rather than contracting.
Residential launches continued to exceed sales for the 16th straight quarter, according to the Knight Frank India assessment, with 92,549 new units entering the market in the third quarter, up 4 percent from the prior year. The gap between launches and sales narrowed to 5,782 units in the period from 10,028 units earlier in the year, suggesting developers have started aligning supply more closely with local demand. Over the first nine months, launches totalled 279,899 units, a 4 percent increase that left new supply ahead of sales by 21,661 units.
Supply adjustments varied by city, the Knight Frank India report stated, with launches climbing 24 percent in Hyderabad and 23 percent in Mumbai while falling 11 percent in Pune and 5 percent in Delhi-NCR. Sales advanced 6 percent in Kolkata and 4 percent in Bengaluru during the quarter, held steady in Chennai and Ahmedabad, and declined 5 percent in Pune. Mumbai led nine-month sales volumes with 72,804 units, a 1 percent rise, followed by Bengaluru at 43,140 units that grew 5 percent and Pune with 36,402 units that stayed level with 2025.
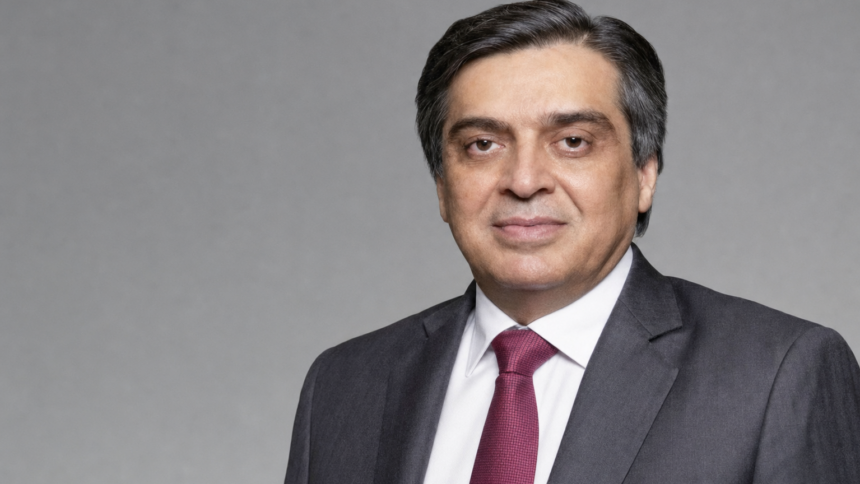
Shishir Baijal, chairman and managing director at Knight Frank India, said in the report that India’s residential market is entering a more discerning phase in which the quality and relevance of supply will matter as much as the strength of demand. He noted that sales held steady in the first nine months of 2026 as the market plateaued after several years of strong growth. Baijal added that combined sales in the seven markets outside Delhi-NCR rose 2 percent year on year while NCR’s 11 percent moderation for the nine-month period was led by the INR 5 crore to 10 crore segment.
The quarters-to-sell metric climbed to 6.1 quarters in the third quarter from 5.8 quarters a year earlier, Knight Frank India data shows, marking the fourth consecutive increase and the highest reading since the second quarter of 2023. The report described the macroeconomic backdrop as still supportive even though monetary policy is no longer contributing additional momentum to the sector. Sales below INR 5 million fell 14 percent to 47,660 units in the first nine months, illustrating how demand has shifted across price bands.